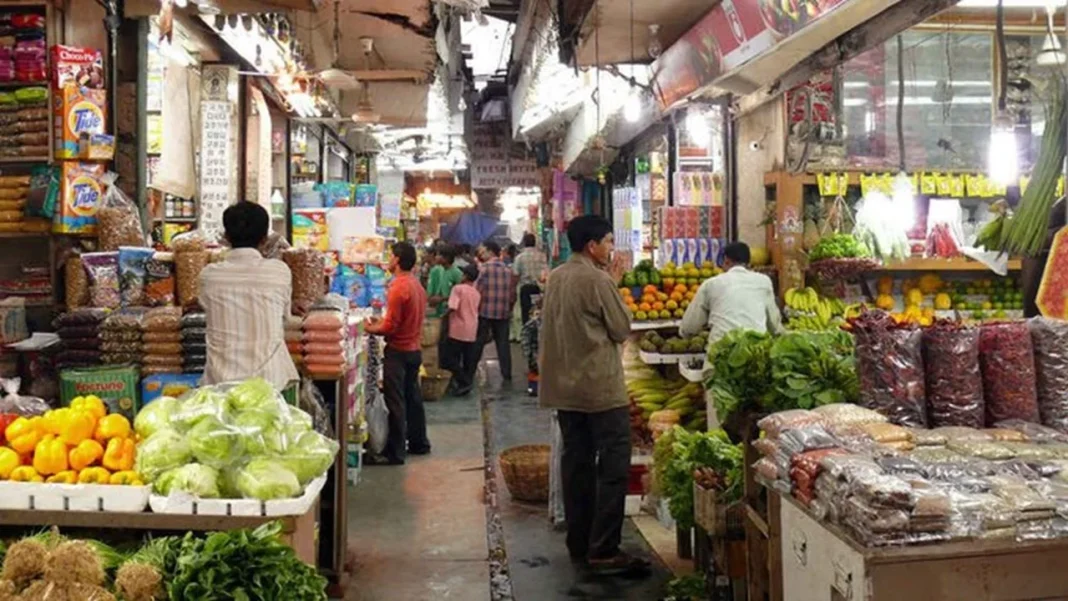

Retail inflation above 6% increases pressure on RBI policy and household spending, but a higher loan EMI still depends on interest rates and contract terms.
India’s October 2026 CPI inflation reached 6.09%, up from September’s final 5.54%. The MoSPI release published on 12 November identifies October’s figure as provisional and puts food inflation at 8.94%.
Key Highlights
- India’s inflation target remains 4%, with a 2%–6% tolerance band.
- One monthly reading above 6% does not constitute formal targeting failure.
- A floating-rate loan’s repayment may change through EMI, tenure or both.
Why Retail Inflation Above 6% Does Not Trigger an Automatic Rate Hike
The 25 March 2026 government notification retains the 4% target and 2%–6% tolerance band from 1 April 2026 to 31 March 2031. Six per cent is the upper boundary, rather than the level policymakers aim to maintain.
The Monetary Policy Committee decides the repo rate after assessing inflation and growth. A monthly inflation release does not itself change borrowing rates.
Indeed, the October MPC resolution already records a 25-basis-point increase to 5.50%, decided on 7 October. That decision preceded the latest CPI release.
The Three-Quarter Accountability Rule
Under the RBI’s published framework, failure occurs when average inflation exceeds the upper tolerance level for three consecutive quarters. It is not a rule about three consecutive monthly readings.
Such failure requires the RBI to report the reasons, proposed corrective action, and expected return to target to the government. It does not prescribe an automatic rate increase of a particular size.
How Repo Rate Changes Reach Loan EMIs
Your loan rate is separate from the RBI repo rate. For a repo-linked floating-rate loan, the benchmark moves with policy, but the agreement’s reset provisions determine when the revised rate applies.
A fixed-rate period does not become floating merely because CPI crosses 6%.
For covered floating-rate EMI-based personal loans, the RBI reset circular requires lenders to communicate increases in EMI or tenure. Borrowers must receive choices involving a higher EMI, longer tenure, or a combination.
Here is a calculated illustration, not a rate forecast. Assume ₹50 lakh outstanding, 240 monthly instalments remaining, and monthly reducing-balance interest, excluding fees.
| Loan Interest Rate | Remaining Term | Approximate Monthly EMI |
| 8.00% | 20 years | ₹41,822 |
| 8.50% | 20 years | ₹43,391 |
At the same remaining term, the EMI rises by about ₹1,569. Keeping the EMI lower through an extended tenure changes the repayment schedule and can increase total interest.
A lender’s notice deserves three checks:
- Benchmark: Confirm whether the loan follows repo, another external benchmark or an internal benchmark.
- Reset date: Identify when the revised interest rate takes effect.
- Repayment schedule: Compare both the EMI and the number of instalments remaining.
An unchanged EMI alone does not prove the loan’s total cost stayed unchanged.
Household Budget Impact Starts With What You Buy
October’s national average hides different experiences. Rural CPI inflation was 6.63%, against 5.41% in urban areas. These are year-on-year measures, not the price increase between September and October.
Food inflation at 8.94% also explains why a grocery-heavy budget may feel more pressure than the headline 6.09% suggests.
For illustration, a ₹10,000 food basket would cost ₹10,894 if its price rose by 8.94% over a year. That calculation assumes the same basket and rate; it is not an estimate of any particular family’s expenses.
Compare quantities as well as receipts. A similar bill after buying less does not show that prices stopped rising.
Two records help separate the pressures:
- Shopping costs: Track the same quantities of regularly purchased essentials.
- Debt costs: Record any revised EMI alongside remaining tenure and interest rate.
The next scheduled CPI release is on 14 December 2026. Another monthly number will update the picture, but an individual household’s spending still needs its own comparison.
Frequently Asked Questions
Does inflation of exactly 6% breach the upper tolerance limit?
No. Six per cent is the upper tolerance boundary; a reading above it exceeds the band. Formal targeting failure also depends on averages across three consecutive quarters.
Does lower inflation mean grocery prices have fallen?
Not necessarily. A lower positive inflation rate means prices are rising more slowly against the comparison period. Falling prices require a decline in the relevant price measure.
Will every home loan EMI rise after a repo rate hike?
No. The effect depends on the loan’s benchmark, reset date, and fixed or floating terms. Some borrowers may face a longer tenure rather than a higher EMI.
Can every floating-rate borrower demand a switch to fixed rates?
The updated RBI circular leaves the fixed-rate switching option to the lender’s board-approved policy. Availability and charges therefore need checking rather than assuming every lender offers it.
How much does 25 basis points change an interest rate?
Twenty-five basis points equal 0.25 percentage points. A loan rate moving from 8% to 8.25% rises by that amount; it does not increase the EMI by 25%.
Explore More RBI Updates, Loan Rates and Rising Prices!
1. What Happens at RBI MPC Meetings?
2. How Do Repo Rates Affect Borrowers?
Uncover how repo rate changes affect borrowers and influence loan repayments and monthly EMIs.
3. What Does 5.50% Mean for Borrowers?
See how the RBI’s 5.50% repo rate affects home loans, fixed deposits and borrowing costs.
4. Why Is India’s Smartphone Market Declining?
Explore India’s smartphone market trends in 2026 and their potential impact on budget phone prices.
5. Why Are Laptop Prices Rising?
Find out what is driving laptop price increases and how changing costs could affect buyers.